
 +90 533 888 29 50


Buying property in North Cyprus carries genuine legal, financial and structural risks that differ significantly from purchasing in most other European destinations. The core issue is not any single problem — it is a combination of contested land ownership history, a jurisdiction that lacks international recognition, and the practical challenges of off-plan purchases and contract registration that even careful buyers sometimes overlook.
This guide covers the full range: disputed property rights, transaction risks, construction risks and ownership costs. It explains what each risk means in practice, which documents help you assess it, and where due diligence stops short of providing a complete guarantee. Purchasing within the local system administered by the Turkish Cypriot authorities is legally possible, and foreign buyers have acquired property there. But the particular circumstances of the territory mean that additional checks are not optional — they are the baseline for any responsible approach to buying here.
Key Takeaways
- The origin of the land title matters as much as its current registration status — always establish the historical category of the plot before proceeding.
- A locally registered title does not automatically extinguish claims arising under another legal system, including that of the Republic of Cyprus or an EU court.
- Permission to Purchase requirements for foreign buyers changed in October 2026; confirm the current rules and statutory deadlines with an independent lawyer before signing anything.
- Off-plan purchases carry an additional layer of risk because the title may not exist in your name at the point of handover, even after you have paid a large proportion of the purchase price.
- Some risks — particularly those arising from the territory’s unresolved political status — cannot be fully eliminated by due diligence, regardless of how thorough it is.
North Cyprus property buying risks: key facts for 2026
| Issue | What buyers should know |
|---|---|
| International recognition | The TRNC is recognised as a state only by Türkiye |
| Main legal risk | Competing claims relating to land owned before 1974 |
| Foreign buyer approval | Permission to Purchase is generally required |
| Contract registration | One-month deadline under Decree No. 119/2026, subject to applicable conditions |
| Transfer fee payment | Within 75 business days of publication of the permission |
| Title transfer | Generally within one year of publication of permission, subject to statutory exceptions |
| Stamp duty | Commonly quoted at 0.5%; confirm the current applicable rate |
| VAT | Commonly 5% on qualifying developer sales; verify applicability |
| Transfer fees | Temporary October 2026 schedule reported as 4%, 5.5% and 6% depending on the foreign buyer’s property sequence |
| Safest historical title category | Pre-1974 Turkish Cypriot title generally carries lower historical ownership-claim exposure |
| Essential protection | Independent legal review before any non-refundable payment |
These figures are a general reference, not a transaction quote. Decree No. 119/2026 is currently scheduled to remain in force until 4 January 2027. Separate transfer-fee amendments published in October 2026 have their own stated validity period. Buyers should obtain written confirmation of the applicable rates and deadlines from an independent lawyer and the relevant authorities.
Is Buying Property in North Cyprus Safe?
The honest answer is that this question cannot be given a single yes or no, and any source that offers one deserves scrutiny. What you can say is that some purchases in North Cyprus complete smoothly, that the local legal system provides a functioning framework for transactions, and that foreign buyers have acquired property there. You can equally say that the territory carries risks which do not exist in EU property markets — and that those risks do not disappear simply because you use a reputable agent or pay a deposit through a solicitor.
The starting point is the political background. Northern Cyprus has been administered by the Turkish Cypriot authorities since 1974, when the island was divided following a military intervention by Turkey. The Turkish Cypriot administration calls itself the Turkish Republic of Northern Cyprus (TRNC), but this entity is recognised as a separate state only by Türkiye. The Republic of Cyprus — the internationally recognised government and an EU member state — considers the north to be occupied territory.
This matters for property buyers because of how it affects the legal standing of transactions. Property transactions in Northern Cyprus are administered under the legal framework of the Turkish Cypriot authorities, which is not recognised by the Republic of Cyprus as a valid basis for transferring ownership of property belonging to another registered owner. The whole island is part of the European Union, but the application of EU law is suspended in areas where the Government of the Republic of Cyprus does not exercise effective control, under Protocol No 10 to the 2003 Act of Accession. The recognition and enforcement of particular rights or court judgments outside Northern Cyprus depend on the applicable law and circumstances of the case. A locally issued title deed should therefore not be treated as conclusive evidence that all competing ownership claims have been resolved.
The UK government advises buyers to obtain independent legal advice and be aware of the serious risks involved, noting that properties may be subject to mortgage charges placed by the original owner, or that there may be outstanding claims by previous owners displaced in 1974.
The critical distinction is between what the local system permits and what other legal systems recognise. Getting a Permission to Purchase approved, having a contract registered at the TRNC land registry, and receiving a title deed are three separate steps — and none of them, individually or together, resolves the question of whether the Republic of Cyprus or any other external jurisdiction would recognise your ownership rights. A buyer who understands this distinction is in a fundamentally better position than one who assumes that completing the local process provides comprehensive legal protection.
Title Deed Risks and Ownership Disputes
A koçan is commonly used to refer to a registered title deed in Northern Cyprus. Buyers must establish exactly which registered parcel and ownership interest corresponds to the property being offered — not every plot is straightforwardly subdivided, and some involve shared or fractional interests that are not immediately apparent from a single document.
The origin of a plot matters because of what happened in 1974. Land that was owned by Greek Cypriot families before the division may subsequently have been allocated or reassigned under the Turkish Cypriot administration’s post-1974 property arrangements. These arrangements did not necessarily involve the consent of the original owners. The original owners or their descendants retain legal rights recognised under international law and the Republic of Cyprus’s legal system, regardless of what the northern administration’s records show.
There are broadly three main categories of title in Northern Cyprus, each carrying a different risk profile. Historical title categories and the form of current registration are separate considerations: a property may have a particular historical title origin while also being registered as an individual unit or as a share in a larger parcel.
Pre-1974 Turkish Cypriot title refers to land that was owned by Turkish Cypriots before the island’s division and registered in their name under the colonial or post-independence land registry. Because this land was already Turkish Cypriot-owned, it is generally considered to carry a lower risk of historical claims by Greek Cypriot owners — but it does not carry zero risk. Boundary errors, inheritance disputes, unregistered charges and other issues can still arise.
Exchange or Equivalent titles generally refer to property allocated under the Turkish Cypriot administration’s post-1974 system to persons who had left property in the south. This allocation did not necessarily involve the consent of the pre-1974 Greek Cypriot owner of the northern property. Consequently, an Exchange title does not establish that the original owner’s rights have been extinguished under the laws of the Republic of Cyprus. Buyers should investigate the particular property’s pre-1974 ownership history and any subsequent claims.
Allocation or Tahsis titles were issued by the northern administration to grant land — often former Greek Cypriot property — to Turkish Cypriot families or settlers, without a formal exchange agreement. Allocation titles may present particularly significant historical ownership risks where the land was previously registered to a Greek Cypriot owner. The level of risk must be assessed against the records and claims relating to the individual parcel.
Beyond the historical category, there is a separate question about how the title is currently structured. An individual title deed means the property has been formally subdivided and registered as a discrete unit. A shared or pro-indiviso title means the property’s legal ownership is expressed as a fraction of a larger plot, which can complicate your ability to mortgage, sell or develop it independently. Condominium-related rights add a further layer involving the management of common areas and facilities.
| Title category | What it generally means | Main concern | What to verify |
|---|---|---|---|
| Pre-1974 Turkish Cypriot | Land registered in Turkish Cypriot ownership before 1974 | Not automatically free of all claims; may have boundary, inheritance or encumbrance issues | Full documentary history of the plot; current encumbrance search at the TRNC land registry |
| Exchange / Equivalent | Property allocated under the post-1974 Turkish Cypriot system to persons who left property in the south; did not necessarily involve consent of the pre-1974 northern owner | Original owner’s rights may not be extinguished under Republic of Cyprus law | The original pre-1974 ownership records, the basis on which the equivalent title was issued, any documented compensation or property-claim proceedings, and any unresolved claims relating to the plot |
| Allocation / Tahsis | Land granted by northern administration, often former Greek Cypriot property | Historical ownership risk must be assessed against individual parcel records; may carry significant exposure where the original owner is identifiable | Full plot history; IPC status if applicable; independent legal assessment of the specific parcel |
| Individual title | Property subdivided and registered as a discrete unit | May coexist with any of the above historical categories | Confirm subdivision is properly registered and matches the physical footprint of what is being sold |
| Shared / pro-indiviso | Ownership expressed as a share in a larger unsubdivided plot | Limits your ability to sell, mortgage or develop independently | Whether individual subdivision is planned, at what cost, and whether other co-owners’ consent is required |
Buyers should ask their lawyer to obtain and assess the available historical ownership records, including pre-1974 records where accessible, and explain any gaps that remain unresolved. Even a photograph of a title deed is not sufficient for assessment. The visible document tells you the current registered status, not the history of how the land came to be registered in that way.
For an explanation of how each title category works in practice, see “North Cyprus title deeds explained“.
Encumbrances present a further complication. The land may carry a mortgage placed by a previous owner, a judicial charge, or rights granted to a third party that are not immediately visible from the face of the deed. These must be searched for separately through the TRNC land registry, and their absence should be confirmed before any payment is made.
Explore Residential complexes in North Cyprus

 Karsıyaka
 from 73м²




Legal Claims and International Exposure
Ownership disputes in Northern Cyprus are not merely theoretical. The Republic of Cyprus’s Ministry of Foreign Affairs has formally set out the legal consequences for foreign citizens purchasing Greek Cypriot-owned property in the occupied area, explaining that transactions conducted without the consent of the original owners may expose buyers to civil liability and, in some circumstances, criminal proceedings under Cypriot law — including under Article 303A of the Criminal Code of the Republic of Cyprus.
The civil risk concerns the possibility that an original owner — or more commonly their descendants — may pursue a claim against the current occupant of a property. Under the law of the Republic of Cyprus, purchasing property that belonged to a displaced Greek Cypriot family does not extinguish the original owner’s rights. A court in the Republic of Cyprus could, in principle, issue a judgment ordering the current occupant to vacate the property or pay damages. The practical question for a foreign buyer is whether such a judgment could be enforced in their home country.
A locally registered title does not automatically resolve claims arising under another legal system.
This is precisely what the Apostolides v Orams case demonstrated within the European Union. In that case, a British couple who had purchased property in Northern Cyprus received a judgment against them in a Cyprus court. The Court of Justice of the EU confirmed in its ruling of 28 April 2009 that, under EU rules on the mutual recognition of judgments, a judgment from a Republic of Cyprus court could in principle be recognised and enforced in another EU member state. This does not mean every buyer faces immediate enforcement action — the practical steps involved are demanding and depend on individual circumstances — but it illustrates that the legal exposure can follow a buyer home, particularly if they are resident in an EU country.
The Immovable Property Commission (IPC) was established by the Turkish Cypriot authorities as a mechanism for original owners to claim compensation, exchange or restitution in relation to properties in the north. The European Court of Human Rights, in its ruling in Demopoulos and Others v Turkey (1 March 2010), found that the IPC represented an accessible and effective domestic remedy for certain categories of claims — which effectively means original owners are expected to pursue claims through the IPC before proceeding to Strasbourg. The implications of any IPC decision depend on its terms, the property concerned and the parties affected. Buyers should not assume that the existence of IPC proceedings or a concluded case necessarily resolves every issue affecting their proposed acquisition.
According to the Republic of Cyprus Ministry of Foreign Affairs, purchasing Greek Cypriot-owned property without the consent of the original owners may constitute a criminal offence under Cypriot law. Criminal proceedings have occurred in specific cases. The Ministry issued a formal warning in December 2025 reporting convictions in May and October 2025 involving transactions or promotional activities relating to Greek Cypriot-owned property, including a sentence of five years’ imprisonment following the October 2025 conviction. These cases involved specific circumstances and should not be read as applying uniformly to all owners of property in the north — but they do demonstrate that the legal exposure is not purely theoretical.
The scenario of reunification adds a further dimension. A negotiated settlement between the two communities would, at some stage, require a determination of property rights across the island. No-one can predict the terms of such an agreement, and it would be speculative to assume that current ownership arrangements in the north would be automatically confirmed, challenged, or compensated in any particular way. Treating reunification as a guaranteed upside for property values is not a sound basis for an investment decision.
This article provides general information and is not a substitute for independent legal advice on a specific property.
Foreign Buyer Restrictions and Permissions
Foreign nationals — people who are not citizens of the TRNC — are generally required to obtain Permission to Purchase (PTP) from the Council of Ministers of the northern administration before a title deed can be legally transferred into their name. This is not a formality: without it, the title cannot be registered in the buyer’s name, and the legal transfer of ownership cannot be completed.
October 2026 regulatory update. Decree with Force of Law No. 119/2026 took effect on 6 October 2026, replacing the earlier Decree No. 89/2026 and continuing several existing requirements for foreign property buyers. The decree is currently scheduled to remain in force until 4 January 2027, unless extended, amended or replaced. Under the decree, foreign buyers within its scope must meet strict requirements for payment of applicable charges, registration of the stamped sale contract and submission of the Permission to Purchase application. The decree provides a one-month period for the relevant registration and application steps and states that non-compliance can result in the contract becoming void. Buyers should have an independent local lawyer confirm the exact deadline, its starting date, the applicable transitional provisions and any exceptions before signing or transferring funds. The relevant requirements are published with reference to Official Gazette No. 196 of 6 October 2026; the precise application of the decree to individual transactions should be confirmed by a qualified practitioner, not from secondary sources.
A separate deadline may apply after Permission to Purchase has been granted. Under Decree No. 119/2026, the relevant title transfer fees must be paid within 75 business days of publication of the permission, failing which the permission may be automatically cancelled. Buyers should ask their lawyer to confirm the applicable deadline and coordinate the payment and title transfer arrangements accordingly.
Deadline for completing the title transfer
Under the rules currently in force, title transfer generally must be completed within one year of the Council of Ministers’ Permission to Purchase decision being published in the Official Gazette. Different starting points or transitional arrangements may apply in specified circumstances, including certain transactions where the purchase price remains outstanding.
Buyers should distinguish three separate events: paying the required fees, obtaining permission and completing the transfer of title. Meeting one deadline does not automatically mean that the others have been satisfied.
Ask your lawyer to identify the exact transfer deadline in writing and explain the consequences of any delay.
The practical implications of the PTP requirement are significant beyond the new deadline rules:
A signed contract is not the same as a completed transfer. Many buyers proceed through reservation, deposit and even full payment on the assumption that the title transfer is a procedural step that will follow in due course. In reality, if Permission to Purchase is refused, or if the application is delayed, the buyer is in a position where they have paid but cannot receive legal ownership. The contract should address this scenario explicitly.
Different rules may apply to apartments and land plots. In some periods, foreigners have been permitted to purchase apartments under a simplified process while stricter limits applied to land. Your lawyer must confirm which regime applies to the specific property you are considering.
Joint purchases require clarity on whose name(s) the application is made in. If you are buying with a spouse or partner who holds a different nationality, the applicable rules may differ for each of you, and the PTP application must reflect the actual ownership structure.
Processing times may vary. Buyers should obtain an up-to-date assessment from their independent lawyer and avoid making financial commitments that assume approval by a particular date.
For a full breakdown of the process and what to prepare, the “North Cyprus Permission to Purchase guide” covers the stages in detail — but check that its content reflects Decree No. 119/2026, as the rules changed in early October 2026.
One scenario that catches buyers out is the purchase of a property that previously changed hands through an assignment of contract — where an off-plan buyer sold their rights under the original contract to a new buyer before the title was issued. In this situation, the PTP history and the contract chain may be more complex, and the incoming buyer may be acquiring rights under a private agreement rather than a registered contract with a clear title history.
Contracts, Deposits and Payment Risks
The sequence in which money changes hands in a North Cyprus property transaction does not always match the sequence in which legal rights are established. Understanding that gap is essential before committing funds.
A reservation agreement may require the seller to withdraw the property from marketing for an agreed period, but the extent of this obligation depends on the written terms and its enforceability. Some buyers treat signing as the beginning of a legal commitment; others assume the deposit is freely refundable if they change their mind. The agreement itself determines which applies. Before signing a reservation agreement and paying any deposit, confirm in writing whether the deposit is refundable if the legal due diligence reveals a problem, if Permission to Purchase is refused, or if you simply decide not to proceed.
Verifying the identity and authority of the seller is not a step that should be delegated to the selling agent. If you are purchasing from an individual, confirm their identity formally and that they have unencumbered legal title to the property. If you are purchasing from a developer, verify that the company exists as a properly registered legal entity, that the person signing has authority to bind the company, and that the company’s financial position does not suggest it may be unable to complete the development.
Payment routing matters. Before transferring any funds, confirm through your independent lawyer that the bank account receiving payment belongs to the correct legal entity — not to an individual acting on behalf of a developer without proper authorisation. Cases where buyers transferred deposits to bank accounts that turned out to be unconnected to the seller are not unique to Cyprus, but the cross-border nature of most North Cyprus transactions makes verification more important, not less.
For a step-by-step overview of the buying process, see “How to buy property in North Cyprus“.
| Purchase stage | Potential problem | Document to check | Buyer protection |
|---|---|---|---|
| Reservation / holding deposit | Deposit treated as non-refundable even if legal issues arise | Written reservation agreement with explicit refund terms | Insist on clear conditions under which deposit is returned; keep amount minimal until legal review is complete |
| Sales contract signing | Contract does not reflect verbal promises about specifications, delivery or price | Draft contract reviewed by independent lawyer before signing | Ensure all agreed specifications, payment schedule and completion date are in the signed contract |
| Payments during construction | Payments made to incorrect entity or against milestones not tied to build progress | Bank account confirmation; developer’s company registration | Link staged payments to verified construction milestones; confirm payment recipient matches the contracting entity |
| Permission to Purchase | Refused or delayed after substantial payment made | Contract clause covering PTP failure | Contract should expressly address refusal, repayment procedures, deadlines and responsibility for any associated costs |
| Title transfer | Title not transferred at completion; encumbrances discovered | Land registry encumbrance search; title history | Agree a legally reviewed completion procedure that coordinates the final payment, discharge of relevant encumbrances and transfer of title, with documentary confirmation of each step |
| Post-completion | Specifications differ from what was promised; utilities not connected | Snagging list; utility connection documentation | Retain a portion of funds, where contractually possible, pending satisfactory completion of snagging and connections |
Currency clauses deserve particular attention. Some contracts in North Cyprus are denominated in GBP or EUR, while others are in Turkish lira or US dollars. If the contract currency and your payment currency differ, you carry exchange rate exposure for every future instalment. A contract price that seemed competitive at the exchange rate prevailing when you reserved may cost significantly more by the time you complete. Compare fees, exchange rates and settlement protections offered by appropriately regulated payment providers. Any foreign-exchange hedging arrangement should be assessed separately for cost, suitability and contractual risk.
If you are buying remotely — without being physically present at each stage — additional care is needed around “Buying property in North Cyprus remotely“. A power of attorney given to someone you have not independently verified, or to an individual connected to the selling agent or developer, does not provide the independent oversight that the name implies. Any power of attorney should be granted to your own lawyer after independent verification of their credentials.
Not sure which type of property fits your budget?
Answer four short questions about your preferred location, budget and property type. Cypria Homes can help you compare available options before you arrange independent legal due diligence.
Find Properties That Match Your Plans
Off-Plan Property and Developer Risks
Buying a property that has not yet been built — or is part-way through construction — introduces a separate category of risk on top of the title and legal issues already covered. In North Cyprus, off-plan sales are common, and many developments offer payment plans structured around construction milestones. That structure can look attractive, but the legal protections available if something goes wrong are materially different from those in most Western European markets.
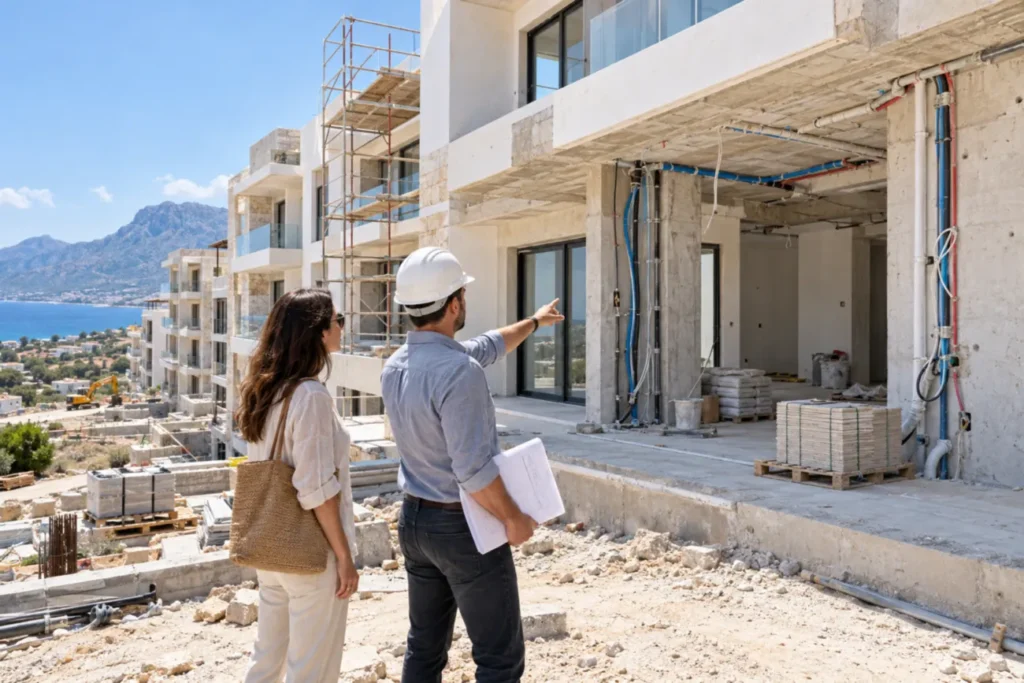
Off-plan vs completed resale: which risks are different?
| Factor | Off-plan property | Completed resale |
|---|---|---|
| Physical inspection | Finished apartment cannot yet be inspected | Actual condition can be surveyed |
| Construction risk | Delays, unfinished works and specification changes | Usually lower, but defects may remain |
| Title availability | Individual unit title may not yet exist | Existing title may be available for verification |
| Payment exposure | Instalments may be paid before completion | Completion payment can often be coordinated with transfer |
| Developer insolvency | Potentially significant exposure | Usually less direct construction exposure |
| Utility connections | May be incomplete | Existing connections can be tested |
| Rental income | Cannot start before usable handover | May start sooner if legally and physically ready |
| Key legal check | Land ownership, permits, development rights and title-issuance arrangements | Existing title, historical ownership, encumbrances and registered alterations |
Neither category is automatically safe. A completed resale can still have serious historical title problems, while a well-documented off-plan development may have clearer contractual protections than a poorly documented resale. Compare the individual property, not only its construction status.
Before Construction
The period before building starts is when most of the critical checks need to happen. A developer’s ability to sell units does not mean it has the legal right to develop the land. Before committing to an off-plan purchase, your lawyer should confirm that the developer holds clear legal title to the land — or a properly documented development agreement from the landowner — and that the land is free of mortgage charges or other encumbrances that could affect the development.
Building permits and planning approvals are separate documents. A planning approval confirms that the development is permitted in principle. A building permit authorises the specific construction to begin. The independent lawyer should identify and verify all planning and building approvals required for the particular development. Where an approval is outstanding, the contract should address the associated risks, payment conditions and consequences of refusal.
The developer’s financial position is difficult for a private buyer to assess independently, but certain indicators are worth requesting: how many units in the development have been sold, whether the development is being funded through pre-sales or through a construction loan, and whether a fixed completion date is contractually binding. A developer who has taken on a large construction loan secured against the land you are buying on could potentially put the property at risk if they default — even if your individual purchase contract is in order.
Before Handover
The period approaching completion carries its own risks. One important risk is a mismatch between the specifications promised at the point of sale and what is actually delivered. Marketing brochures, show-apartment presentations and verbal statements should not be assumed to form part of the binding construction specifications. However, depending on the applicable law and circumstances, misleading representations made before signing may still give rise to legal remedies. To reduce uncertainty, buyers should ensure that all important promises concerning dimensions, finishes, amenities and completion dates are expressly recorded in the signed contract or its annexes.
Utility connections — electricity, water, drainage — may not be in place at the date the developer nominates as the handover date. In some developments, this can take additional time beyond the formal completion date. If you are buying to rent immediately, or if your mortgage or lease arrangement depends on the property being habitable at a specific point, confirm the utility connection status and the contractual commitment around it as a risk to manage, rather than assuming it will be resolved automatically.
Can unpaid property taxes delay utility connections?
Under the rules currently in force, unpaid taxes and transfer-related fees may prevent a property from receiving permanent or temporary water and electricity connections, subject to the statutory exception for construction-site connections.
This means that a property may be physically finished but still face obstacles to normal occupation. Before handover, buyers should ask their lawyer and the relevant utility providers to confirm which taxes, connection charges and administrative approvals remain outstanding.
Do not assume that receiving the keys automatically means the property is ready for residential use or rental.
The following is a hypothetical example intended to illustrate how these risks can affect an individual purchase; it is not a documented transaction. A buyer has paid 70% of the purchase price on a new-build apartment in a coastal development. The developer formally hands over the keys on the contractually agreed date, but the wastewater system for the development is not connected to the municipal network and a central swimming pool shown in the sales material is incomplete. The purchase contract defines completion as the transfer of keys, not the delivery of a fully functional property with all promised amenities. The buyer’s available remedies will depend on the contract, the applicable law and the evidence of any representations made before the sale. Independent legal review is therefore important before signing, particularly where the definition of completion differs from the buyer’s expectations.
| Risk | Evidence to request | Warning sign | Recommended action |
|---|---|---|---|
| Developer lacks title to the land | Copy of land title or development agreement | Developer delays or refuses to provide land ownership documentation | Do not proceed until title and development rights are confirmed in writing |
| Building permit not in place | Copy of the issued building permit | Permit described as “expected” or “in process” at time of sale | Make permit issuance a condition of any substantive payment |
| Developer has mortgaged the land | Land registry encumbrance search | No encumbrance search offered; developer requests large early payments | Independent search before first major payment; seek a clause in the contract addressing mortgage discharge |
| Completion date not contractually binding | Signed contract with fixed completion date and delay penalties | “Expected completion” stated in marketing but not defined in contract | Insist on a fixed completion date with meaningful financial consequences for delay |
| Specifications differ from brochure | Signed specification schedule annexed to contract | Specifications described only in marketing materials, not in the contract | Ensure every promised feature is listed in writing in the contract or annexe |
| Utility connections incomplete at handover | Written confirmation from utility providers | Developer describes connections as “the buyer’s responsibility” | Clarify in the contract whether connections are the developer’s responsibility and by what date |
| Snagging defects unresolved | Independent snagging survey before handover | Developer pressures buyer to sign off handover before defects are addressed | Commission an independent snagging survey; retain leverage over final payment where contractually possible |
Comparison of new-build properties

 Catalkoy, Kyrenia Eastfrom 442м²

Hidden Costs and Financial Risks
The asking price of a property in North Cyprus is not the total cost of acquiring it. Additional costs can represent a substantial proportion of the purchase price, and buyers who budget only for the headline figure often find themselves committed to a transaction they cannot comfortably complete.
Property purchase costs in Northern Cyprus may include title transfer fees, stamp duty, VAT where applicable, registration charges and professional fees. Temporary changes to foreign-buyer transfer fees were reported in October 2026, so older figures quoted in property advertisements may no longer apply. Buyers should request a written, itemised transaction-cost estimate from an independent lawyer, showing the statutory rate, valuation basis, payment deadline and any exemption or transitional rule applicable to their particular purchase. The estimate should distinguish payments due at contract registration from those payable at title transfer.
Stamp duty on the contract and any associated registration requirements must be checked against the legislation applicable on the signing date. Failure to comply with statutory payment or filing requirements may have serious consequences for the contract and the buyer’s legal protection — including in relation to the Decree No. 119/2026 deadlines discussed above.
VAT may or may not apply depending on the nature of the transaction — whether the seller is a developer selling a new property, and whether any construction is involved. These are questions for a lawyer, not for the selling agent.
Legal fees for independent advice are a non-negotiable part of the budget. The cost will depend on the complexity of the transaction, but treating this as an area to economise is a false economy. The role of your lawyer in conducting due diligence on title, reviewing the contract and managing the PTP application is central to the entire process.
| Cost category | When it arises | Why it matters | What to confirm |
|---|---|---|---|
| Title transfer fee | At title registration | May represent a significant percentage of the declared purchase price; temporary rates were in effect in October 2026 | Obtain a written cost estimate from an independent lawyer confirming the applicable rate, valuation basis, and any exemption or transitional provision |
| Stamp duty | At contract registration | Statutory payment and filing requirements must be met to protect the contract and the buyer’s legal position | Confirm the current rate and deadline with your lawyer; particularly important given Decree 119/2026 |
| VAT (where applicable) | On new-build properties sold by a developer | Increases the effective purchase cost beyond the stated price | Clarify whether VAT is included in or additional to the quoted price |
| Independent legal fees | Throughout the transaction | Essential; not optional | Agree scope and fee structure with your lawyer at the outset |
| Utility connection charges | At handover or shortly after | Costs can be substantial for new developments; sometimes unexpected | Confirm which connections are the developer’s responsibility and what the buyer will need to pay |
| Annual maintenance / service charges | Ongoing from occupation | Applies to developments with shared facilities; can rise over time | Ask for the current annual charge and review the management company’s track record |
| Currency conversion costs | At each payment | Sterling or euro payments converted to another currency carry exchange rate risk | Compare fees, exchange rates and settlement protections from appropriately regulated payment providers |
| Buildings insurance | Annually from completion | Required by lenders; strongly advisable otherwise | Confirm whether a group policy exists and its adequacy |
| Furniture and fitting out | At occupation | New-build properties are often unfurnished | Budget realistically; do not treat the yield calculator as reliable until costs are accounted for |
Example: How much could a £150,000 apartment actually cost?
The following illustrative budget assumes a foreign individual buying their first property in Northern Cyprus for £150,000. It uses the temporary transfer-fee rate reported in October 2026, together with commonly quoted stamp duty and VAT rates. It is not an official transaction assessment.
| Cost | Resale example | New-build example |
|---|---|---|
| Purchase price | £150,000 | £150,000 |
| Transfer fee — illustrative 4% | £6,000 | £6,000 |
| Stamp duty — illustrative 0.5% | £750 | £750 |
| VAT — illustrative 5% if applicable | £0* | £7,500 |
| Legal fees — assumed budget | £1,500 | £1,500 |
| Infrastructure and utility allowance | £1,000 | £2,500 |
| Illustrative total | £159,250 | £168,250 |
| Above purchase price | 6.2% | 12.2% |
The resale example assumes no VAT is payable on the particular transaction. This must be verified rather than inferred solely from the property’s age.
This example excludes any additional buyer-paid agency fees, financing charges, furnishing, insurance, currency-conversion losses and property-specific expenses. Legal fees and infrastructure allowances are illustrative assumptions, not statutory tariffs. The transfer fee may be assessed using an official valuation rather than simply the agreed purchase price. Ask your lawyer to calculate the actual charges and payment schedule before signing.
A further point on rental yields: gross yield and net return are not the same figure. A developer or agent quoting a percentage rental yield may be referring to a gross figure — potential annual rental income divided by the purchase price — rather than a return after management fees, service charges, vacant periods, maintenance and applicable taxes. Net return can be significantly lower, and in a development with high service charges and limited occupancy outside the summer season, the difference matters substantially. For detail on the current applicable taxes, see “North Cyprus property taxes and fees“.
Resale, Rental and Location Risks
Buying property is one decision; selling it is another. In North Cyprus, resale is possible but the market for secondary properties involves constraints that do not exist in most EU destinations, and several factors specific to the territory affect how easily and at what price you can sell.
The pool of potential buyers for any property in North Cyprus is narrower than in many European markets, partly because the jurisdiction’s unusual status deters some buyers from the outset, and partly because mortgage and other acquisition finance options may be more restricted than in established EU property markets. Eligibility and availability depend on the lender, the borrower’s circumstances, the title and the property — buyers should not assume that finance will be readily available on standard terms.
A disputed or complex title history may make resale more difficult. Some prospective buyers may prefer a property with a documented pre-1974 Turkish Cypriot ownership history over one with an Allocation title, although this preference cannot be assumed to apply to every buyer or transaction. The title history is one factor among several that shapes the available market for any individual property.
Selling before you have received the title deed in your name — for example, assigning your contractual rights to another buyer while you are still in the PTP process or waiting for an off-plan development to complete — is legally possible in some circumstances but subject to restrictions. The original contract may prohibit assignment, the developer’s consent may be required, and the incoming buyer will inherit all the uncertainties you have been living with. The price achievable through an assignment may be affected by contractual restrictions, developer consent requirements, outstanding payments and the availability of buyers.
From a rental perspective, North Cyprus has a genuine short-term rental market concentrated around the summer season. Short-term rental demand varies by area, season and visitor segment; buyers should examine recent occupancy and accommodation-market data for the specific location rather than assume demand from particular nationalities or visitor groups. Year-round occupancy is more challenging in most locations. In areas with substantial new development, competition between similar rental properties may affect occupancy and achievable rates.
The following is a hypothetical scenario intended to illustrate how these risks can affect an individual purchase. A buyer purchases a one-bedroom apartment in a resort development near Famagusta on the basis of a projected annual rental yield. The developer’s figure assumed full summer occupancy and a consistent off-season rate. In practice, the development’s management company retained a commission, the service charge was higher than initially quoted, and the apartment sat unoccupied for several months of the year. The effective return was materially lower than projected — not because anything went wrong legally, but because the financial model was constructed optimistically.
Example: How a projected 8% gross yield can change
Suppose a buyer purchases an apartment for £150,000 and receives a rental projection of £12,000 per year, equivalent to an 8% gross yield on the purchase price.
Actual income and expenses could look different:
| Item | Illustrative annual amount |
|---|---|
| Advertised rental income | £12,000 |
| Actual rental income after vacancies | £9,000 |
| Management fees — assumed 20% of actual rent | −£1,800 |
| Service charges | −£1,500 |
| Maintenance allowance | −£600 |
| Insurance and other operating costs | −£300 |
| Income remaining before tax | £4,800 |
| Return on £150,000 purchase price, before tax | 3.2% |
This is a hypothetical calculation, not a North Cyprus market average or a prediction. It excludes acquisition costs, financing, income tax and major repairs. The actual result depends on the property, rental regulations, occupancy, management contract and ownership costs.
Location affects resale value and rental performance in ways that are difficult to predict. A coastal development that is a significant drive from the nearest hospital, supermarket or international school may be attractive to holiday visitors but less so to residents or long-term tenants. Before committing to a location based on its scenic qualities or projected yields, spend time there outside the summer season and assess the infrastructure, transport links and community facilities independently.
The legal status of the specific plot always matters more than the general reputation of an area. A property with a strong title in a less fashionable location may be a better long-term asset than a prime-location property with a complicated ownership history.
How to Reduce Your Buying Risks
No property acquisition is entirely free of legal or financial risk, and Northern Cyprus presents additional jurisdictional and historical title considerations that require specific due diligence beyond what is standard in other markets. But the difference between a buyer who has completed thorough due diligence and one who has not is substantial — both in terms of the problems they are likely to encounter and in their ability to address those problems if they arise.
The sequence below reflects the order in which checks should happen, not the order in which a seller or developer will typically present information to you.
Step 1: Establish the specific plot and its history. Before spending any money, get the exact land registry reference for the plot you are considering and ask your lawyer to obtain and assess the available historical ownership records, including pre-1974 records where accessible. Ask your lawyer to explain any gaps that remain unresolved and whether any IPC proceedings relate to this particular plot.
Step 2: Appoint your own independent lawyer. An independently appointed lawyer should act under a clearly defined professional engagement that identifies the buyer as the client and sets out the scope of legal advice, due diligence and transaction representation. The lawyers recommended by developers or selling agents may be perfectly competent, but their relationship with the introducing party creates a structural conflict of interest.
Step 3: Verify the seller’s identity and authority. This includes confirming that the person or company you are contracting with has legal title to what they are selling, that no other person has an interest in the property, and that anyone signing on behalf of a company has the documented authority to do so.
Step 4: Confirm the applicable foreign buyer rules. Your lawyer should advise you whether you need Permission to Purchase, what documents the application requires, and — particularly given Decree No. 119/2026 — what the current registration and submission deadlines are. Do not rely on information provided by the selling agent for this step.
Step 5: Commission a physical inspection and, for off-plan, review the build specifications. For an existing property, a structural survey or technical inspection by a qualified professional is advisable. For an off-plan purchase, review the detailed specification schedule before signing, and compare it against what is described in the marketing materials.
Step 6: Review the contract before signing. The contract should be reviewed by your independent lawyer in advance, with particular attention to payment milestones, the completion date, consequences of delay, what happens if PTP is refused, and what the handover conditions specify.
Step 7: Confirm the statutory registration and permission deadlines. Before signing, ask your lawyer to identify the applicable deadline for stamping and registering the sale contract and submitting the Permission to Purchase application. Obtain written confirmation that the required filings have been completed and that the relevant receipts and registration records are available. Missing a statutory deadline may affect the validity or enforceability of your contract.
Step 8: Conduct final checks before completion. Immediately before the final payment, carry out a fresh encumbrance search, revisit the property to confirm its condition matches what you contracted for, and confirm that any outstanding snagging items have been addressed.
Documents to request before committing to a purchase
| Document or record | What it helps establish |
|---|---|
| Current title deed and parcel reference | Registered ownership and exact property identification |
| Historical title information | Pre-1974 ownership background and subsequent changes |
| Land Registry encumbrance search | Mortgages, charges and other registered restrictions |
| Seller identity or company registration | Whether the contracting party is properly identified |
| Evidence of signing authority | Whether the person signing can bind the seller |
| Planning approval | Whether the proposed development has the necessary planning authorisation |
| Building permit | Whether the construction has the required permit |
| Final approval or completion documentation, where applicable | Whether the completed building meets the relevant administrative requirements |
| Draft sale contract and annexes | Payment obligations, specifications, completion and refund terms |
| Contract stamping and registration receipts | Evidence that the required registration steps were completed |
| Permission to Purchase records | Application status, decision and publication date |
| Written tax and fee estimate | Amounts payable, applicable rates and statutory deadlines |
Not every document will exist at the same stage of an off-plan purchase. If a required document is unavailable, ask your independent lawyer to explain why, what legal consequence follows and whether payment should be postponed until it is obtained.
The following are red flags that should stop the transaction until a satisfactory explanation and supporting documentation are provided:
- The seller or developer refuses to provide the title history or land registry documentation.
- The legal origin of the plot cannot be clearly established.
- The developer objects to independent professional inspections of the property or the documentation.
- A large, non-refundable payment is required before any legal review has been completed.
- The contract does not specify a clear completion date or a mechanism for dealing with delays.
- Characteristics described in the marketing materials are not reflected in the contract or specification schedule.
- Legal inconsistencies or encumbrances are identified that the seller is unable to explain clearly and in writing.
Some of these issues can be resolved through negotiation or additional documentation. Others are more fundamental. The distinction that matters is between a deficiency that can be corrected before exchange and one that indicates an underlying problem with the property or the transaction that cannot be contracted around.
If the seller cannot provide the documents needed to assess a material risk, do not treat the missing information as a minor formality.
Property risk assessment: when should you pause a purchase?
| Situation | Recommended response |
|---|---|
| Historical ownership cannot be established | Pause the transaction until an independent lawyer provides a documented assessment |
| Unresolved claim by a pre-1974 owner | Obtain specialist legal advice covering the Republic of Cyprus and cross-border exposure |
| Seller refuses an encumbrance search | Do not make a non-refundable payment |
| Developer cannot demonstrate development rights | Do not proceed until the legal basis is verified |
| Required building permit is missing | Postpone substantive payments pending legal review |
| PTP eligibility is uncertain | Obtain a written assessment before signing |
| Individual title is not yet available | Verify subdivision, existing rights and the contractual route to transfer |
| Service charges are unclear | Obtain a written schedule and review management arrangements |
| Developer promises guaranteed returns without supporting contract terms | Treat projections as unverified marketing claims |
| Seller insists on immediate non-refundable payment | Stop and obtain independent legal advice |
This table is a screening tool, not a legal classification of properties as safe or unsafe. A satisfactory explanation of one issue does not resolve unrelated title, planning or contractual risks.
Ready to explore properties with a clearer understanding of the risks?
Tell us your budget, preferred location and whether you are looking for a completed home or an off-plan development. We’ll help you narrow down the options so you can decide which properties are worth reviewing with an independent lawyer.
Final Thoughts
The risks of buying property in North Cyprus are real, specific and layered. The most fundamental is not the exchange rate, the developer’s reputation or the delivery schedule — it is the origin of the land title and the legal consequences that flow from it across different jurisdictions.
Careful due diligence can substantially reduce the risks that are verifiable: the title history, the encumbrances, the developer’s legal standing, the contract terms, and the permissions required. What due diligence cannot do is eliminate the residual uncertainty that comes from the territory’s unresolved political and legal status. That uncertainty has persisted for fifty years. A buyer who understands what they are accepting — and who has the financial resilience to tolerate the worst-case outcome — is making a genuinely informed decision. A buyer who proceeds on the assumption that everything will be fine because the agent said so is not.
Do not pay a non-refundable deposit while material legal or financial questions remain unanswered. Do not sign a contract without independent legal review. And do not allow the attractiveness of the price, the location or the payment plan to substitute for the conclusions of a qualified lawyer who has seen the actual documents for the specific property you are considering.
If you are in the early stages of exploring properties in the area, Cypria Homes can help you identify options across Kyrenia, İskele, Esentepe, Famagusta and beyond, and compare what is available at different price points. The legal checks, however, are the work of an independent lawyer — and that step comes before any financial commitment.
 Real estate in Georgia
 Real estate in Montenegro
 Real estate in the UAE
 Real estate in Bali
 Real estate in Thailand
 Real estate in Spain
 Real estate in Saudi Arabia
 Real estate in Turkey
 Real estate in Zanzibar
 +90 533 888 29 50
 hello@cypria.homes
 Karsıyaka Sokak 8, Girne


 Get catalogue of TOP-7 objects